In this guide
Review the written denial and policy, organize evidence, request reconsideration and check applicable deadlines. A contractor can document damage, but cannot guarantee coverage or a successful appeal.
Keep it handy
A free printable for this guide
Save a copy for your fridge or binder. No email needed.
Insurance conversation planner
Gather questions, claim contacts and next steps before you speak with your insurer.
Read the checklist online
Use this to prepare for a call about coverage, an estimate, a denial or a claim update.
Ask your insurer to explain your own policy and any deadlines in writing. This is an organizer, not legal advice or a promise of coverage.
Questions to ask
- What policy wording applies to this loss, and what documents do you still need?
- What are the next steps, contact person and applicable submission dates?
- How should I document urgent work, damaged items and temporary living expenses?
- If an amount or decision is disputed, can you explain it in writing and describe the review process?
Space to fill in
- Insurer / claim reference
- Contact / phone or email
- Call date / person spoken to
- Questions / documents still needed
- Written explanation / policy section
- Next action / owner / due date
Reference guidance
Make it your own
Keep the details together
Damage documentation organizer
Record what happened, follow room-by-room photo prompts and export notes and photos in one organized record.
Start your damage recordWhat to do when a water damage claim is denied
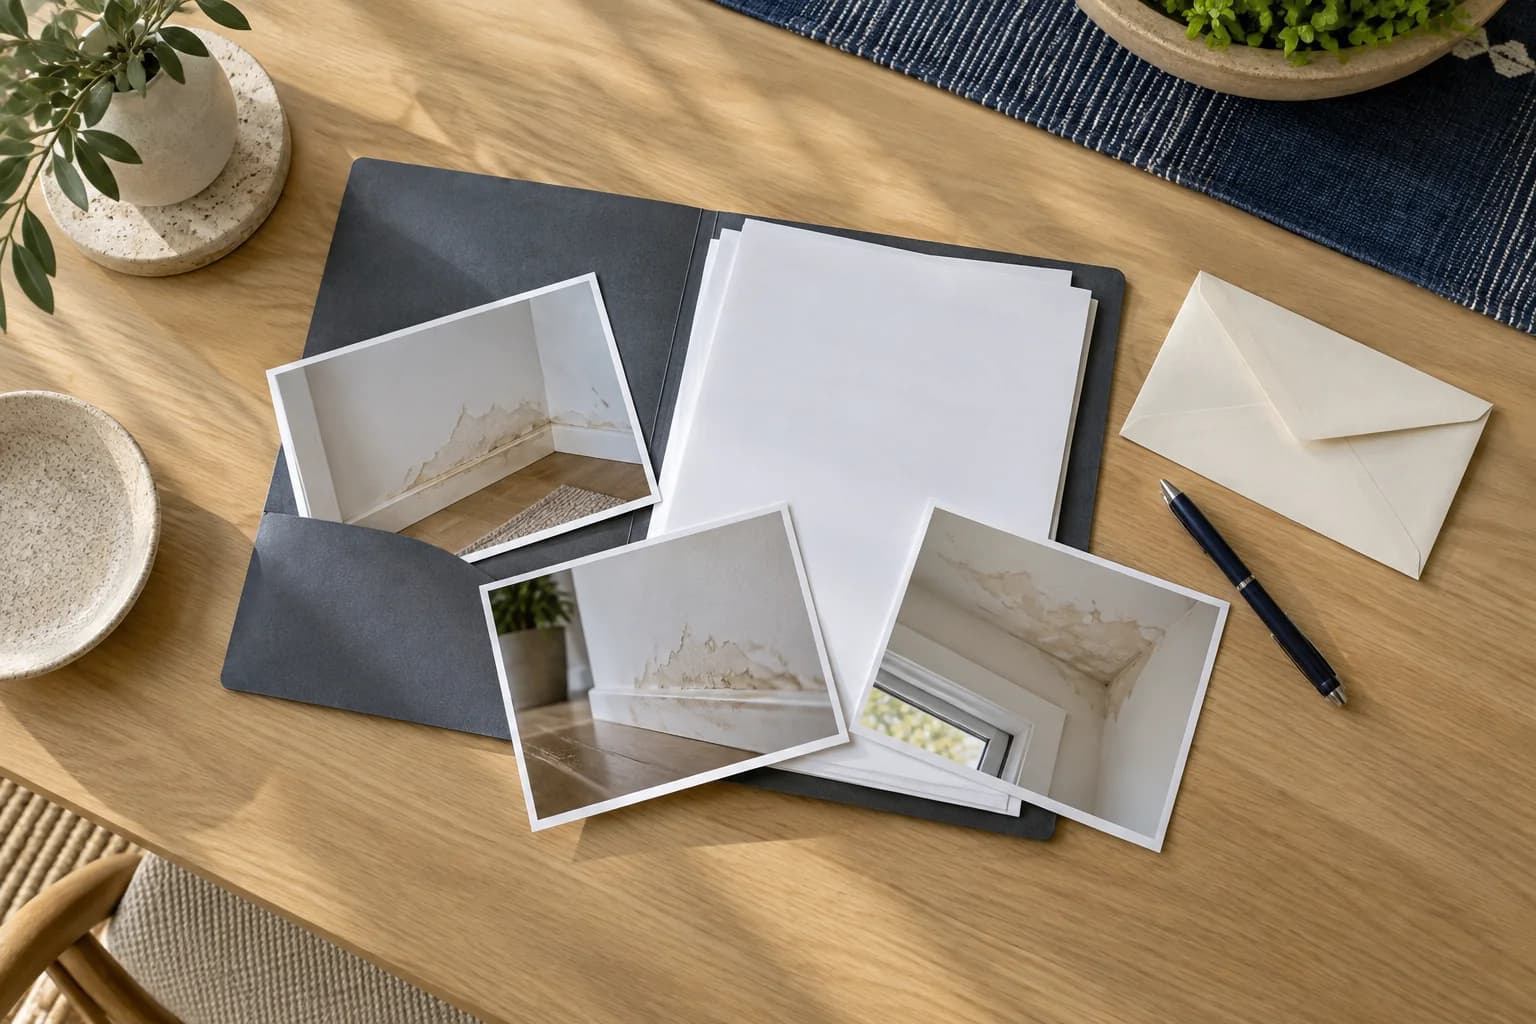
A denial is a decision to review carefully. Ask the insurer for its written reasons and the policy provisions it relied on, then compare them with your records of the loss. A contractor can describe observed damage and repair needs; that assessment does not determine insurance coverage.
1. Start with the denial letter and complete policy
Keep the denial letter, declarations page, policy forms, endorsements and claim number together. Identify whether the dispute concerns the cause of damage, an exclusion, a limit, missing information or the repair amount. The date you discovered damage and the date it began may be different. Record both honestly and distinguish what you observed from what remains unknown.
The California Department of Insurance explains written denials and options for disputed settlements in its Residential Property Claims Guide.
2. Assemble a clear evidence packet
- Create a timeline of discovery, reporting, inspections, emergency work and correspondence.
- Keep original photographs and videos, with room names and a short description of what each image shows.
- Include relevant maintenance receipts, prior repair records and inspection reports.
- Ask the contractor for the observed damage, measurements, moisture readings and itemized repair scope. Ask them to separate observations from opinions about the cause.
- Save estimates, invoices and receipts for temporary measures. Record discarded items and follow the insurer's instructions when safe and practical.
The damage documentation organizer helps collect room-by-room notes and photographs. Keep a copy of the exported record with your claim correspondence.
3. Request a review in writing
Use the insurer's stated review channel. Identify the decision you dispute, explain the specific correction requested and attach the relevant supporting records. Ask what information is still needed, who is handling the review and when you should expect an update. Keep delivery confirmation and a copy of everything sent.
A useful request is: "Please review the denial dated [date] for claim [number]. The decision states [reason]. Attached are [records] that I believe address that reason. Please explain how these records and the cited policy provisions affect the decision." Do not fill gaps with assumptions about when a leak started or why a material failed.
4. Check the applicable deadlines
There is no blanket 30-day appeal-decision rule established by this guide. California claims-handling rules address different events: acknowledgement, responses to communications, investigation, acceptance or denial, and payment. The starting event, exceptions and any justified extensions matter. https://www.insurance.ca.gov/01-consumers/105-type/95-guides/03-res/res-prop-claim.cfm's claims-handling guide explains those distinctions.
Ask for the requirements and deadlines that apply to your claim in writing. A request for review or a regulatory complaint should not be assumed to extend a proof-of-loss or lawsuit deadline. Obtain qualified advice promptly if a deadline is approaching.
5. Use the right help for the dispute
If the adjuster cannot resolve your concern, request review by the claims manager. You can also ask the California Department of Insurance for assistance or submit a complaint. Include the denial, policy, correspondence and a concise description of the unresolved issue. A complaint does not promise a coverage change or payment.
For help with claim presentation or a disputed repair amount, check whether a California-licensed public adjuster is appropriate. For policy interpretation, legal deadlines or possible litigation, consult a California attorney. Before hiring anyone, verify their license and review the written scope, fees and termination terms. Do not assume a standard fee percentage, a fee cap or that one professional's contract permits work by another.
Keep safety and repairs separate from the coverage dispute
Discuss necessary temporary protection with your insurer and contractor. Record the condition before work when safe and retain receipts. Do not enter unsafe rooms, climb onto a damaged roof or delay emergency services to collect evidence. Agree in writing who authorizes the work and how it will be paid if insurance does not cover some or all of it.
Save The Day Restoration can document affected materials and prepare a restoration scope in Los Angeles and Orange County. Call (562) 246-9908 to discuss the property and current availability. Coverage decisions belong to the insurer under the policy; legal representation and public adjusting are separate services.
Common questions
Does suddenly discovering a leak make it covered?
No. Discovery alone does not establish when the damage began or how the policy applies. Provide accurate observations and ask the insurer to explain its decision against the policy.
Is outside water always flood damage?
No. The cause and policy definition matter. Do not classify a loss solely by whether water entered from outside. Ask the insurer to explain which policy provisions apply.
Can a contractor guarantee that an appeal will succeed?
No. A repair assessment can support your records, but it cannot guarantee coverage or reverse an insurer's decision.
How we prepare and update our guides
Related serviceWater Damage RestorationEmergency water extraction & dryingAbout Save The Day Restoration
Save The Day Restoration is a locally owned, IICRC-certified restoration and reconstruction company serving all of Los Angeles and Orange County. The team coordinates water, fire, and mold restoration and reconstruction, including specialist work when needed. Licensed (CSLB #1049188), bonded, and insured, with 24/7 emergency response.
Call (562) 246-9908